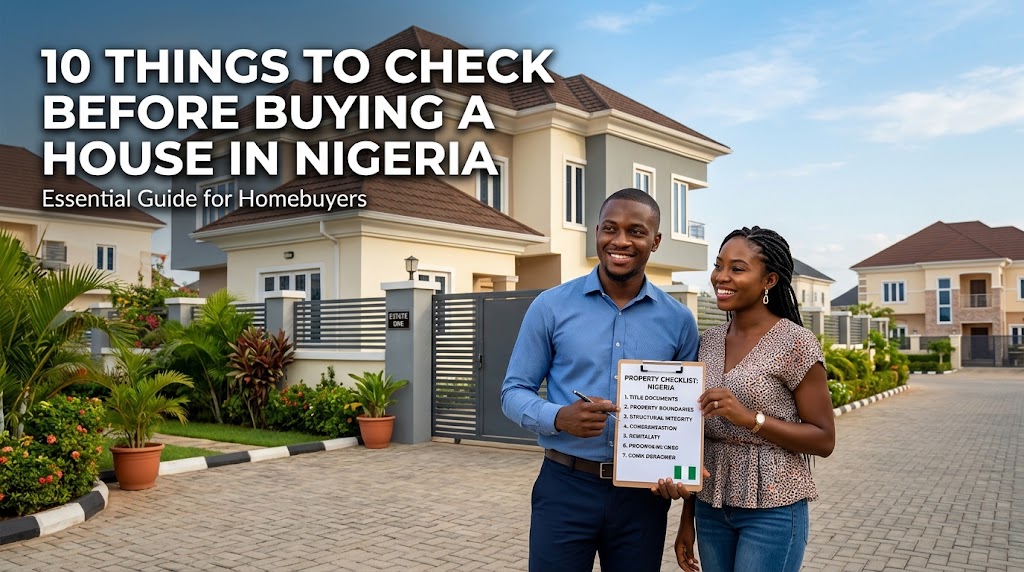

Buying a house in Nigeria is a major financial decision that requires careful planning, proper documentation, and thorough property inspection. Whether you are purchasing your first home, investing in real estate, or buying a property for your family, knowing what to check before buying a house in Nigeria can help you avoid costly mistakes, land disputes, and fraudulent property transactions.
Nigeria’s real estate market offers numerous opportunities, from affordable residential properties to luxury homes in cities such as Lagos, Abuja, Port Harcourt, Benin City, and Ibadan. However, not every property advertised for sale is legally secure, structurally sound, or worth the asking price.
Before paying a deposit or signing a property agreement, here are 10 important things to check before buying a house in Nigeria to protect your money and make a confident investment.
1. Verify the Property’s Ownership and Title Documents
One of the most important things to check before buying a house in Nigeria is the legal ownership of the property.
Before making any payment, confirm that the seller has the legal right to sell the house. Request copies of the property’s title documents and have a qualified property lawyer verify their authenticity.
Depending on the property, relevant documents may include:
- Certificate of Occupancy (C of O).
- Registered Deed of Assignment.
- Governor’s Consent, where applicable.
- Registered survey plan.
- Deed of Conveyance for relevant historical transactions.
- Allocation letter or other relevant government-issued documents.
The documents required will depend on the property’s location, ownership history, and applicable state laws.
Do not assume that a property is genuine simply because the seller presents a C of O or another official-looking document. The documents should be independently verified with the appropriate land registry or relevant government authority.
Pro tip: Engage a property lawyer before making a commitment. Proper title verification can help protect you from buying a disputed property or one the seller does not have the authority to transfer.
2. Conduct a Search at the Relevant Land Registry
Having title documents is not enough. You should also conduct an independent search to establish the property’s legal status.
A land registry search can help determine whether the property has an identifiable registered title, whether the seller’s claimed ownership matches available records, and whether registered mortgages, encumbrances, or other interests affect the property.
Depending on the location and circumstances, further investigations may be necessary to check for pending litigation, government acquisition, competing claims, or restrictions on transfer.
For example, if you want to buy a house in Lagos, your lawyer should verify the relevant records through the appropriate Lagos State land administration authorities. For properties in Abuja, confirm the applicable records and requirements with the relevant Federal Capital Territory authorities.
Do not rely solely on photocopies supplied by the seller, an agent’s assurances, or a family member’s claim of ownership.
Why this matters: A thorough property search can help reveal legal problems before you invest your savings in a house.
3. Confirm the Survey Plan and Property Boundaries
A survey plan identifies the location, boundaries, dimensions, and other relevant details of a parcel of land. It is an important part of verifying the land on which a house stands.
Before buying a property, engage a registered surveyor to inspect the land and confirm that its physical boundaries correspond with the available survey records.
You should also establish whether the property encroaches on neighbouring land, a public road, a drainage corridor, or a designated right of way.
In some areas, buyers may unknowingly purchase properties with disputed boundaries or structures extending beyond the seller’s actual land.
Where necessary, ask the relevant survey authority to verify the survey plan and investigate whether the land falls within a government acquisition or restricted area.
Pro tip: Never rely entirely on fence lines, pillars, or an agent’s verbal description to establish the legal boundaries of a property.
4. Inspect the Structural Condition of the House
A house may look attractive in photographs or during a viewing but still have serious structural defects.
Before buying, arrange for a qualified building professional, such as a structural engineer or experienced building surveyor, to inspect the property.
Pay particular attention to:
- Foundation and walls: Look for significant cracks, settlement, dampness, or signs of structural movement.
- Roof and ceiling: Check for leaks, damaged roofing sheets, sagging ceilings, and water stains.
- Electrical installations: Inspect wiring, sockets, distribution boards, and earthing arrangements.
- Plumbing: Test taps, toilets, water pipes, drainage, and wastewater systems.
- Doors and windows: Check that they open properly, close securely, and show no signs of excessive deterioration.
- Finishing and fittings: Inspect floor tiles, plastering, paintwork, kitchen cabinets, and bathroom fixtures.
For newly built properties, request relevant construction approvals and available completion or inspection records.
For older houses, pay special attention to hidden defects that may require expensive repairs after purchase.
Why this matters: A professional inspection can help you estimate repair costs and negotiate a fair price before completing the transaction.
5. Check the Location and Neighbourhood
The location of a property affects your comfort, security, transportation costs, resale value, and potential rental income.
Before buying a house in Nigeria, visit the neighbourhood at different times of the day. If possible, visit during the rainy season or after heavy rainfall to understand how the area handles water.
Consider the following factors:
- Accessibility to major roads and public transportation.
- Distance to your workplace, schools, hospitals, and markets.
- Availability of electricity, water, and internet services.
- Road conditions and drainage systems.
- Security and general neighbourhood conditions.
- Noise levels, traffic congestion, and nearby commercial activities.
- Planned road projects or other developments that may affect the property.
If you are purchasing a house as a real estate investment, research the demand for rental properties in the area and compare similar houses currently available for rent or sale.
A cheaper property in an inconvenient location may eventually cost more in transportation, maintenance, and resale difficulties.
Pro tip: Speak with residents and neighbours to learn about flooding, security issues, water supply, and other practical concerns that may not be obvious during a short inspection.
6. Investigate Flooding, Drainage, and Environmental Risks
Flooding is an important consideration when buying a house in Nigeria, especially in locations with poor drainage, low-lying terrain, or a history of heavy rainfall.
A property that looks dry during the dry season may experience severe flooding during the rainy season.
Before purchasing, investigate the property’s history and examine the surrounding environment for warning signs such as blocked drains, erosion, waterlogged roads, and nearby waterways.
Check whether the house is located close to a river, floodplain, erosion-prone slope, or other environmentally sensitive area.
Also inspect the foundation and lower walls for dampness, peeling paint, water stains, and evidence of previous flooding.
Ask current occupants and nearby residents whether water enters the building or surrounding compound during heavy rainfall.
Depending on the location, you may also need professional drainage or environmental assessments.
Why this matters: Flooding can damage buildings, destroy household property, increase insurance or maintenance costs, and reduce a property’s resale value.
7. Confirm Building Approvals and Planning Compliance
Before buying a house, confirm that the building was constructed in accordance with the relevant planning regulations and approved building plans.
Depending on the location, the property may require development permits, building plan approval, or other regulatory authorisations. Additional requirements may apply to properties in estates, government layouts, or designated development zones.
Ask the seller for available approvals and have a qualified professional verify them with the relevant planning authority.
Check whether the existing building matches its approved plans and whether extensions, additional floors, converted spaces, or other alterations were properly authorised.
For properties in gated estates, also review applicable estate rules, development restrictions, and any outstanding compliance issues.
Unauthorised construction may expose the buyer to enforcement action, alteration requirements, penalties, or other complications.
Pro tip: Do not assume that a completed building is automatically compliant simply because people are already living in it.
8. Calculate the Total Cost of Buying the House
The advertised price is not always the total amount you will spend when buying a house in Nigeria.
Additional expenses can significantly increase your purchase budget, so calculate the full cost before committing.
Potential costs include:
- Property lawyer’s professional fees.
- Estate agent or agency commission.
- Survey and title verification expenses.
- Applicable registration and consent fees.
- Applicable taxes and other government charges.
- Mortgage processing and valuation fees, where relevant.
- Renovation and immediate repair costs.
- Estate service charges and outstanding utility bills.
The exact charges depend on the property’s location, transaction structure, financing arrangements, and applicable laws.
For example, a house advertised for ₦50 million could require a substantially larger budget once transaction costs and necessary repairs are included.
Ask the seller or agent for a clear breakdown of the purchase price and any additional charges. Have your lawyer or financial adviser verify which fees apply before you pay.
Why this matters: Understanding the total acquisition cost helps you avoid financial pressure after the transaction and ensures that you can comfortably maintain the property.
9. Investigate the Seller, Developer, and Estate Agent
A genuine property should be supported by a credible seller and a verifiable ownership or transfer process.
Before paying anyone, establish who owns the property, who is authorised to sell it, and who will receive your money.
If the seller is an individual, verify their identity and ensure that their ownership claim is consistent with the property records.
If the house belongs to a family, company, estate, or deceased property owner, your lawyer should establish who has the legal authority to complete the transaction and what consents or authorisations are required.
For properties sold by developers, investigate the developer’s track record, completed projects, construction quality, and history of delivering properties to buyers.
If an estate agent is involved, confirm their identity and authority to represent the seller.
Be cautious when you encounter:
- Pressure to make immediate payment without proper verification.
- Prices that appear unusually low compared with similar properties.
- Refusal to provide relevant ownership documents.
- Requests to pay into an unrelated person’s account.
- Conflicting information about the seller or property’s ownership.
- Promises of guaranteed returns without credible supporting evidence.
Important: Do not transfer money simply because an agent claims that another buyer is ready to pay. Complete the necessary checks and ensure that your payment arrangements are properly documented.
10. Review the Sale Agreement Before Making Payment
The sale agreement establishes the terms and conditions under which the property will be transferred to you.
Before signing, engage a property lawyer to review the agreement and ensure that it accurately reflects the transaction.
The agreement should clearly identify the parties, describe the property, state the agreed purchase price, outline the payment schedule, and specify the obligations of both buyer and seller.
It should also address relevant matters such as:
- The documents the seller must provide.
- The process and timing for transferring ownership.
- Responsibility for applicable taxes, fees, and outstanding charges.
- Existing mortgages, encumbrances, or other interests.
- Conditions for completing the transaction.
- Consequences of default or failure to complete.
- The agreed handover date and possession arrangements.
Where a deposit is required, ensure that the amount, purpose, payment recipient, and applicable refund or forfeiture conditions are clearly documented.
After completion, make sure the appropriate transfer documents are executed and that the necessary consent, stamping, registration, or other perfection steps are completed as applicable.
Pro tip: Do not sign a document you do not understand, and do not rely on verbal promises that are missing from the written agreement.
Bonus Tip: Research the Property’s Market Value
Before making an offer, compare the house with similar properties in the same neighbourhood.
Consider the property’s size, location, age, construction quality, access roads, available facilities, legal status, and current market demand.
Where necessary, engage a qualified estate surveyor and valuer to provide an independent valuation.
A property advertised below the market average is not automatically a bargain. It could have title problems, structural defects, poor access, or other issues that justify the lower price.
Likewise, an expensive property is not necessarily a good investment.
Compare several properties, assess their advantages and disadvantages, and negotiate based on reliable information rather than emotional attachment or an agent’s claims.
Common Mistakes to Avoid When Buying a House in Nigeria
Even experienced buyers can make costly mistakes when they rush into a property transaction. Avoid these common errors:
- Buying without title verification: Always investigate the ownership documents independently.
- Skipping professional inspection: Arrange a physical inspection before committing to the purchase.
- Ignoring flooding risks: Investigate drainage, flood history, and the surrounding environment.
- Paying before confirming ownership: Verify the seller’s authority to sell before transferring funds.
- Ignoring additional expenses: Budget for legal fees, applicable government charges, repairs, and maintenance.
- Relying only on an agent: Use independent legal and technical professionals.
- Failing to document payments: Keep receipts, signed agreements, and records of all transactions.
- Overlooking resale potential: Consider future demand, neighbourhood development, and property maintenance costs.
Conclusion
Buying a house in Nigeria can be a rewarding decision when you approach the process with proper research, professional guidance, and careful financial planning.
From verifying title documents and checking property boundaries to inspecting the building, investigating flooding risks, and reviewing the sale agreement, every step helps reduce the possibility of costly mistakes.
Whether you want to buy a family home, a luxury property, or a house for rental income, never pay for a property based solely on attractive pictures, an agent’s promises, or a seller’s assurances.
Take your time, verify the facts, and seek professional advice before completing the transaction.
Are you looking to buy a house in Nigeria? Explore available property listings, compare prices, discover suitable neighborhood, and take the next step towards finding a home that meets your needs and budget.
Your dream home starts with an informed decision.
Leave a Reply